Strategy
The Sunk Cost Trap in a Half-Built Property Portfolio
Off-plan payment plans quietly let money already spent decide money not yet spent. How the sunk cost trap works in a half-built portfolio, and the one test to run at each payment.
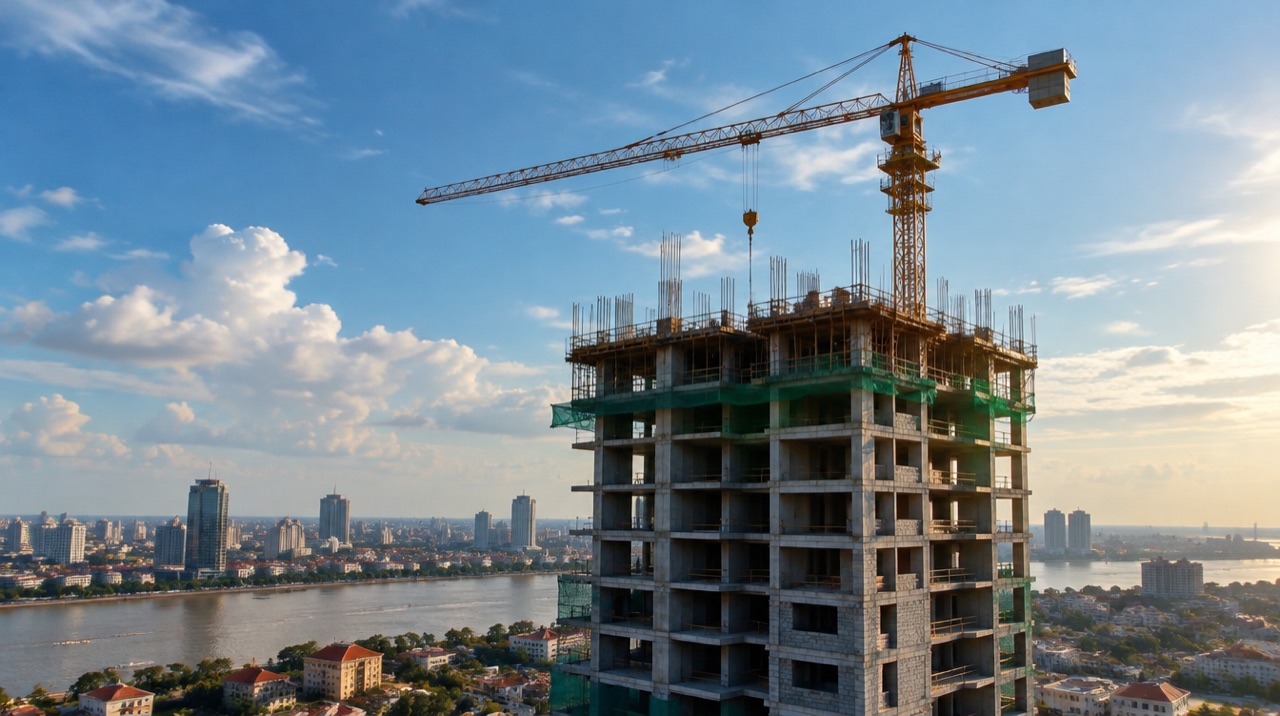
In a standard off-plan plan, as much as 90 percent of a unit's price can reach the developer before the building is finished. The installments arrive on a schedule, and by the time you collect a key, most of your capital is already committed. The arrangement is ordinary. What it does to judgment is not. This is where the sunk cost trap does its quietest damage, and a half-built portfolio is its natural home.
Picture the position many active off-plan buyers end up in. Not one unit but several, spread across two or three projects at different stages. One tops out next quarter. One is still a slab and a sales gallery. One handed over last year and is renting below the original projection. Every few months another payment falls due, and each one feels less like a fresh decision than a defense of the ones already made.
The trap, in a single rule
Behavioral finance is clear about this. A sunk cost is money already spent that no future choice can recover, and it should carry no weight in a forward decision. The only question that matters at any milestone is whether the next dollar, committed today, earns an acceptable return from today's starting point. What you paid before is a fact about the past. It is a receipt, not an argument for what to do next. Off-plan makes this unusually hard, because the payment schedule is a psychology as much as a cash-flow plan. Money leaves the account in visible increments over years, and each one deepens the sense of commitment. By the time the market tells you something real, that a district softened, that resale went thin, that the yield came in light, you are already most of the way in.
The one test to run at every milestone
Disciplined buyers run a single test at each payment. Set aside everything already paid. Imagine the unit appeared today at its current stage, with its current completion risk, its current rent, and its current resale market. Would you commit the remaining installments to buy it now, on those terms? If the honest answer is yes, keep paying. If it is no, the remaining payments are not protecting the earlier ones. They are adding to the error. Most people cannot run this cleanly, because the earlier payments keep intruding and the mind insists that stopping wastes what is already in. It does not. The prior capital is spent under every scenario, whether you continue or walk. The choice is only ever about the money still under your control.
Escalation, one installment at a time
The trap rarely announces itself. It works through small, reasonable-sounding steps. A payment falls due on a project that has slipped, and you pay, because the alternative feels like admitting a mistake. The next payment arrives, larger in cumulative terms, and the same logic applies with more force, because now there is more to defend. That is escalation of commitment, and it is how a portfolio that should have been trimmed at 30 percent exposure ends up fully paid at 90, defended all the way down by the very capital that should have been the signal to stop.
Read the book, not the position
A half-built portfolio is not one decision. It is a set of independent forward decisions that happen to share an owner, and treating it as a single emotional whole is what keeps weak positions alive. Read it unit by unit:
- Complete the units where the forward return still holds.
- Hold and let the ones whose yield survives the net numbers, after vacancy, management, service charge, and withholding tax.
- Release the ones, even at a realized loss, whose capital and attention would earn more elsewhere in the same market.
Releasing at a loss is the hardest of the three and the one the trap most reliably prevents, because a realized loss converts a paper judgment into a closed fact. But the loss happened when the market moved, not when you acknowledged it. Recognition is not the wound. It is the treatment.
Decide before the emotion arrives
The real defense is not willpower at the milestone. It is a rule written before it, in a calm quarter with no payment due. Before entering an off-plan position, set the conditions under which you would stop: a delay beyond a defined point, a resale market below a defined depth, a net yield beneath a defined floor. Put those triggers in the file alongside the payment schedule, so the decision to continue or exit is made by your earlier, unemotional self rather than the version standing at the next payment with pride attached. It costs nothing to write the rule in a quiet quarter and a great deal to improvise one in a soft market with an installment due.
Phnom Penh in 2026 is exactly the kind of reset that tests these rules, with prices off roughly 30 percent after a tourism slowdown rather than any break in the fundamentals. A market like this rewards buyers who price each remaining payment on its own forward merit and treat completing, holding, and walking as three ordinary outcomes. This is general education on investment discipline, not advice on your portfolio. If you are holding off-plan positions and want a candid, unit-by-unit read before the next payment goes out, the investinphnompenh.com team is happy to work through it with you, with no pressure to act.
Get a personal answer
Ask us anything about the Cambodian market. We answer within one business day, in English, Russian, Chinese or Spanish.
Talk to an AdvisorMarket Insights
 Strategy
Buying in a Down Market: The 2008 Lesson for Phnom Penh
Every cycle, the best entry points feel the most uncomfortable. Here is what the recovery after 2008 can teach a patient buyer looking at Phnom Penh in 2026.
 Strategy
The Patient Capital Playbook: How to Buy Through a Property Downturn
A calm, repeatable method for deploying capital in a falling market. It rests on preparation, a margin of safety, and a hold measured in years rather than months.
 Strategy
Why Cash Buyers Have the Advantage in a Soft Market
When credit tightens and confidence drains away, liquidity becomes the scarcest asset in the room. Here is how cash converts into speed, certainty, and a better price.