Strategy
Staging for Sale vs Rent: The Real Economics Behind the Furniture
Staging to sell is a one-time marketing cost. Furnishing to rent is depreciating capital you live with for years. Confusing the two quietly drains net yield.
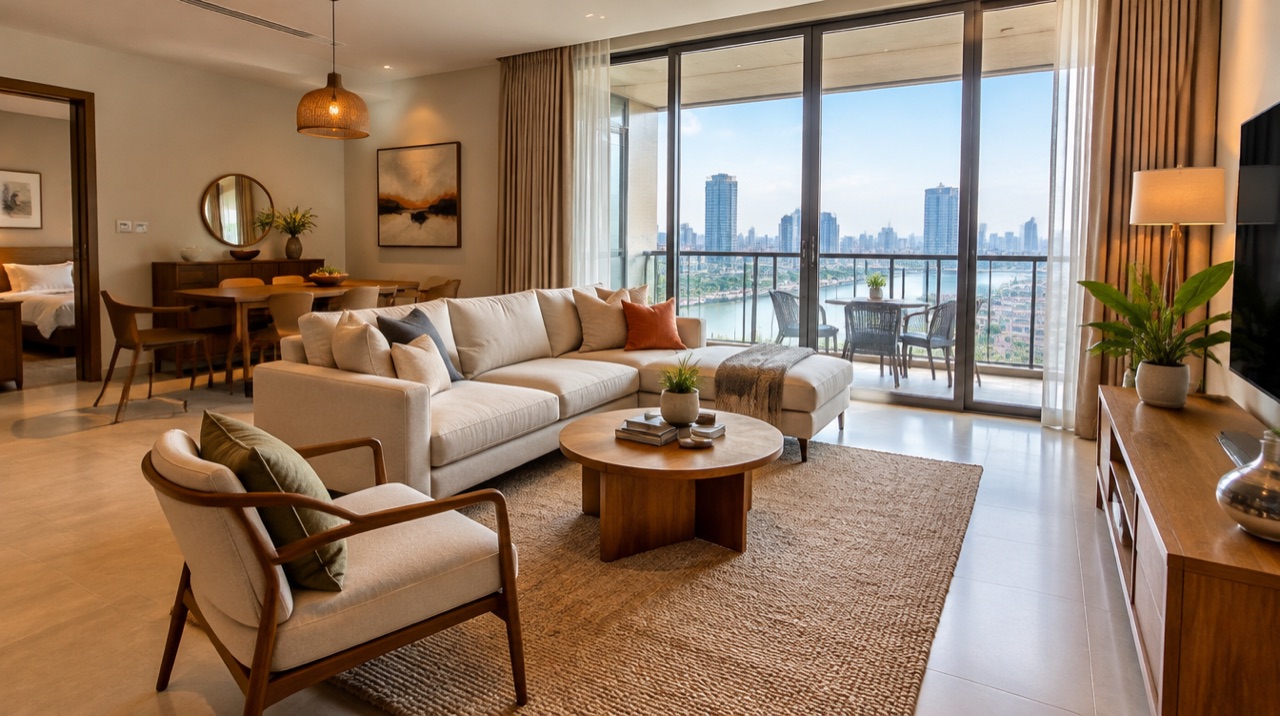
Sixty to ninety days is the working life of most furniture brought into a unit that is being staged for sale. It arrives, it photographs well, it holds the room through the showing window, and then it leaves. Staging a rental runs on a completely different clock. The furniture stays, and it stays for years.
Staging to sell and furnishing to rent usually get filed under one heading. They are not the same decision. One is built for a single event. The other is built to be used every day until it wears out, and the gap between those two facts is where money quietly leaks.
Two different assets
Staging for sale exists to do one thing, which is to shorten the distance between listing and closing. Its whole value is realised at a single moment, the sale, and after that the furniture has no further job. Nothing in the room needs to survive a second tenant. A rental fit out is the opposite. It is a working asset sitting inside an income producing one, used daily by someone who is paying to use it. That single difference reorganises every choice that follows.
The economics of a single event
Price a sale staging as a marketing cost, because that is what it is. A vacant unit might carry a setup in the low thousands of dollars, held across a sixty to ninety day window. The return shows up in two places only: days on market, since furniture helps a buyer picture themselves in the room, and price, since a finished space supports a firmer asking position than an empty one.
Both returns are captured at exit and never again, which is what makes durability irrelevant here. A piece that photographs well and would fall apart in eight months is a sensible buy for a sale, because it will never see month eight. Appearance is the entire specification. It also argues for a light touch: staging the three rooms that decide a showing, the living room, the main bedroom, and the kitchen, captures most of the effect for a fraction of a full unit cost.
The economics of a held asset
Now hold the same unit and rent it, and every assumption inverts. The furniture becomes capital. It is bought once, it depreciates, and it has to be replaced on a schedule. A full fit out for a two bedroom condo might sit between 8,000 and 15,000 dollars depending on tier. Spread that across a four or five year replacement cycle, and it is the annual carrying figure, not the sticker price, that belongs in the yield calculation.
Durability now decides everything. A tenant is not imagining a life in the room, they are producing wear in it. What matters is cost per usable year, not cost on day one, and a sturdier piece that survives three tenancies is often cheaper than a photogenic one that survives a single tenant. The rental side also needs a discipline the sale side never does, a small annual set aside for the pieces that will fail on schedule, so replacement lands as a planned line rather than a surprise against yield.
The furnished premium, net not gross
A furnished unit usually commands higher rent than an empty one, and that premium is the whole reason owners furnish. It is real, and it is rarely as clean as it looks, because furnishing moves the unit into a different tenant pool, typically shorter stay, expatriate, or corporate. That pool carries its own arithmetic.
- Gross premium: the headline bump a furnished listing can ask over a bare one.
- Turnover: shorter average stays mean more voids and more re letting between tenants.
- Replacement: soft furnishings on a four to five year clock, plus the items that break or walk out.
- Net premium: what is left after all of the above, and the only figure worth deciding on.
What this looks like in Phnom Penh
In the Phnom Penh tier that serves expatriate and corporate tenants, furnished is closer to the default than to an upgrade, so the real question is not whether to furnish but at which tier, because the tier selects the tenant and the tenant sets the vacancy. On a unit whose gross yield sits near eight percent, the difference between a fit out that holds tenants and one that churns them can move net yield by more than the furniture ever cost. Rents here are quoted and paid in US dollars, so a foreign owner carries no local currency risk on that income, and rental income taxed at the resident ten percent rate rather than a higher non resident rate keeps more of each dollar.
The furniture that sells a unit and the furniture that rents one are answering different questions, one asked once and the other asked for years. Deciding which asset you are building before you spend tends to mean spending less and keeping more. If you want to run that math on a specific unit before furnishing it, our advisors are happy to help, with no pressure either way.
Get a personal answer
Ask us anything about the Cambodian market. We answer within one business day, in English, Russian, Chinese or Spanish.
Talk to an AdvisorMarket Insights
 Strategy
Buying in a Down Market: The 2008 Lesson for Phnom Penh
Every cycle, the best entry points feel the most uncomfortable. Here is what the recovery after 2008 can teach a patient buyer looking at Phnom Penh in 2026.
 Strategy
The Patient Capital Playbook: How to Buy Through a Property Downturn
A calm, repeatable method for deploying capital in a falling market. It rests on preparation, a margin of safety, and a hold measured in years rather than months.
 Strategy
Why Cash Buyers Have the Advantage in a Soft Market
When credit tightens and confidence drains away, liquidity becomes the scarcest asset in the room. Here is how cash converts into speed, certainty, and a better price.